Health Insurance for Self Employed 26 Year Olds
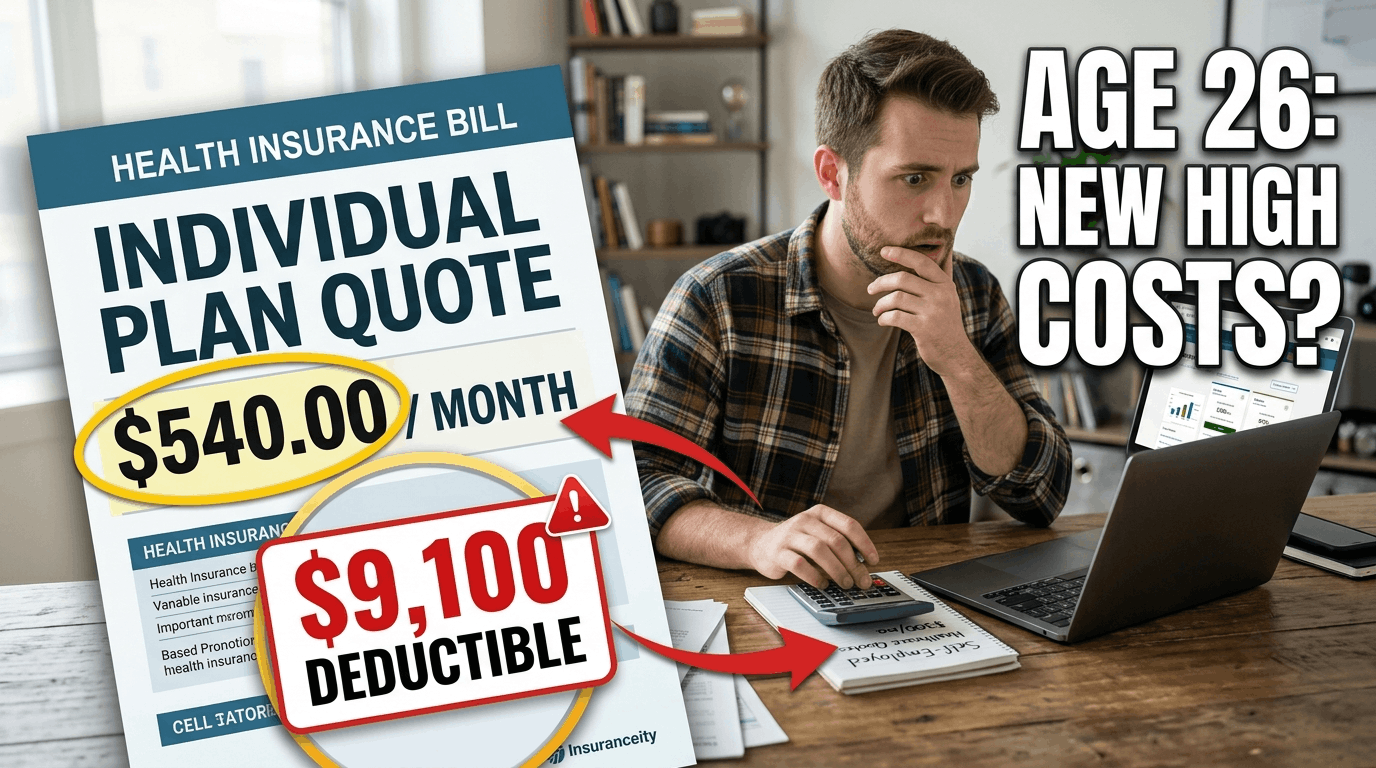
Turning 26 usually means one thing for your health coverage: you’re off your parents’ plan and on your own. If you’re also self-employed — freelancing, running a small business, or doing gig work — finding health insurance for self employed 26 year old can feel more complicated than a typical job-based enrollment. There’s no HR department handing you a benefits packet. The good news is that the individual insurance market is built for exactly this situation, and with the right approach, you can find coverage that fits both your health needs and your income.
The Core Problem: No Employer Plan to Fall Back On
When you work for yourself, you lose access to the biggest advantage most workers have: an employer that partially pays your premium and handles enrollment paperwork. Self-employed individuals are fully responsible for finding, comparing, and paying for their own coverage. This makes understanding your options — and your potential subsidies — more important than ever.
Why This Matters More at Age 26
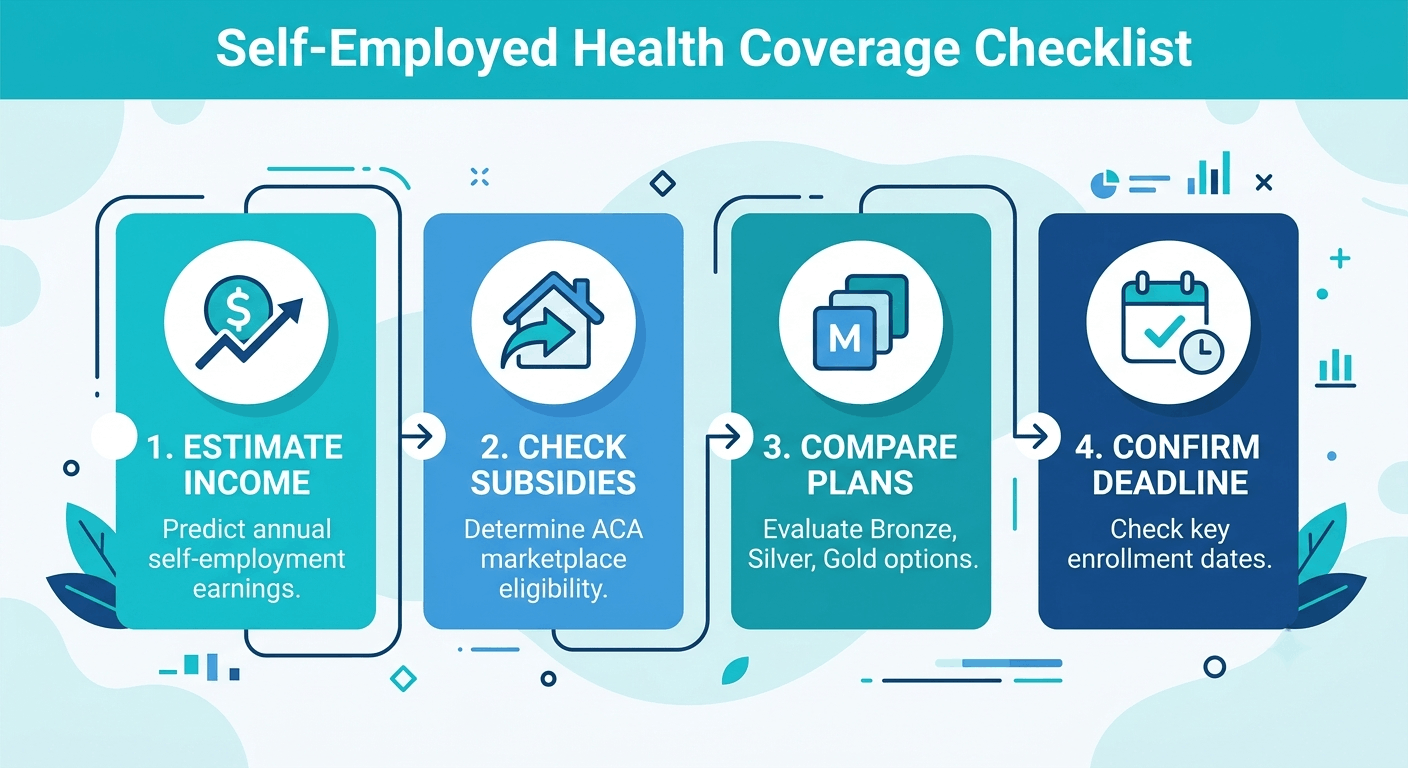
Turning 26 typically coincides with losing eligibility on a parent’s plan, which under the ACA usually happens at the end of your birthday month or the end of the year, depending on the plan. If you’re already self-employed at this point, that transition can feel sudden, so it helps to start comparing options a month or two ahead of your cutoff date.
Read more: Health Insurance Subsidies 2026: Who Qualifies & How Much You Save
Coverage Options for Self-Employed Young Adults
1. ACA Marketplace Plans
The federal or state health insurance marketplace is usually the first stop for freelancers and independent contractors. Because eligibility is based on your income rather than employment status, many self-employed people qualify for premium tax credits that lower monthly costs significantly.
2. Health Savings Account (HSA)-Eligible Plans
If you choose a High-Deductible Health Plan (HDHP), you may be able to pair it with a Health Savings Account, which offers a tax-advantaged way to set aside money for medical expenses.
3. Professional or Trade Association Plans
Some industries offer group coverage through professional associations or freelancer unions, which can sometimes provide better rates than buying purely as an individual.
4. Short-Term Health Plans
These can serve as a temporary bridge for healthy individuals, but they typically exclude pre-existing conditions and essential health benefits, so they work best as a stopgap rather than a long-term solution.
State Laws and Regional Differences
Marketplace rules and available insurers differ by state. States running their own exchanges (such as Covered California, Pennie in Pennsylvania, or NY State of Health) may have different enrollment deadlines, subsidy calculations, or plan options than the federal HealthCare.gov marketplace. Always confirm details through your specific state’s official marketplace.
Read more: Best Health Insurance Companies of 2026, Compared
Health Insurance for Self Employed 26 Year Olds / Cost Factors to Consider
Several variables shape what health insurance for self employed 26 year old actually costs:
- Reported income: Marketplace subsidies are calculated using your estimated annual income, which can fluctuate for freelancers — so accurate income projections matter.
- Self-employment health insurance deduction: Self-employed individuals may be able to deduct health insurance premiums on their federal tax return, which can meaningfully offset costs (a tax professional can confirm your eligibility).
- Plan metal tier: Bronze plans have lower premiums but higher out-of-pocket costs; Gold and Platinum plans cost more monthly but cover more per visit.
- Deductible and HSA compatibility: If you want to pair coverage with an HSA, you’ll need to select a qualifying HDHP.
- Network access: Freelancers who travel or work remotely may prioritize PPO plans for broader provider access over cheaper, more restrictive HMOs.
Comparison Table: Coverage Options at a Glance
| Coverage Option | Approx. Monthly Cost | Enrollment Window | Best For |
|---|---|---|---|
| ACA Marketplace Plan | Varies (subsidies available) | Open Enrollment or 60-day SEP | Most self-employed individuals, especially subsidy-eligible |
| HSA-Eligible HDHP | Low to moderate premium | Open Enrollment or 60-day SEP | Freelancers wanting tax-advantaged savings |
| Association/Trade Group Plan | Varies by group | Depends on association terms | Self-employed workers in a qualifying trade or industry |
| Short-Term Health Plan | Low | Anytime (limited duration) | Healthy individuals needing a temporary bridge |
Video Review:
Health Insurance for Self Employed 26 Year Olds (FAQs)
Q1: Can self-employed people get subsidies on the ACA marketplace?
A: Yes. Marketplace premium tax credits are based on your estimated household income, not your employment type, so many self-employed individuals qualify, especially in the early stages of building a business.
Q2: Can I deduct my health insurance premiums if I’m self-employed?
A: In many cases, self-employed individuals can deduct premiums on their federal tax return, but eligibility depends on your specific tax situation — a tax professional can confirm what applies to you.
Q3: What happens if my freelance income changes during the year?
A: You can typically update your estimated income through the marketplace at any time, which may adjust your subsidy amount and help you avoid owing money back at tax time.
Q4: Is a short-term health plan a good long-term option for freelancers?
A: Generally, no. Short-term plans are designed as temporary bridges and often exclude pre-existing conditions and essential health benefits, so most freelancers use them only while transitioning between other coverage.
Conclusion
Being self-employed doesn’t mean going without solid health coverage — it just means taking a more active role in finding it. For a health insurance for self employed 26 year old situation, the ACA marketplace is usually the strongest starting point, especially with income-based subsidies that can make coverage more affordable than expected. As a next step, visit your state’s official health insurance marketplace to estimate your subsidy eligibility and compare plans before your coverage window closes.
About the Author
This article was researched and written by the editorial team at GoInsurancePolicy.com, dedicated to providing clear, accurate, and up-to-date insurance guidance for American consumers, including freelancers and independent contractors. Our content is reviewed for accuracy against current federal and state insurance regulations. This is not a substitute for personalized advice from a licensed insurance professional or tax advisor.
Disclaimer: This article is for general informational purposes only and does not constitute financial, legal, tax, or insurance advice. Insurance laws, plan availability, subsidy eligibility, and pricing vary by state and change over time. Please consult a licensed insurance agent, a tax professional, or your state’s official health insurance marketplace before making coverage decisions.